Federal Cannabis Registration Is Now a Capital Raising Question
By Peter Ingersoll, Principal at Safe Harbor Equity Inc. and Ready4DEA
WASHINGTON, D.C. — For Cannabis companies preparing to raise capital, federal registration is becoming a question that belongs near the beginning of the investor conversation.
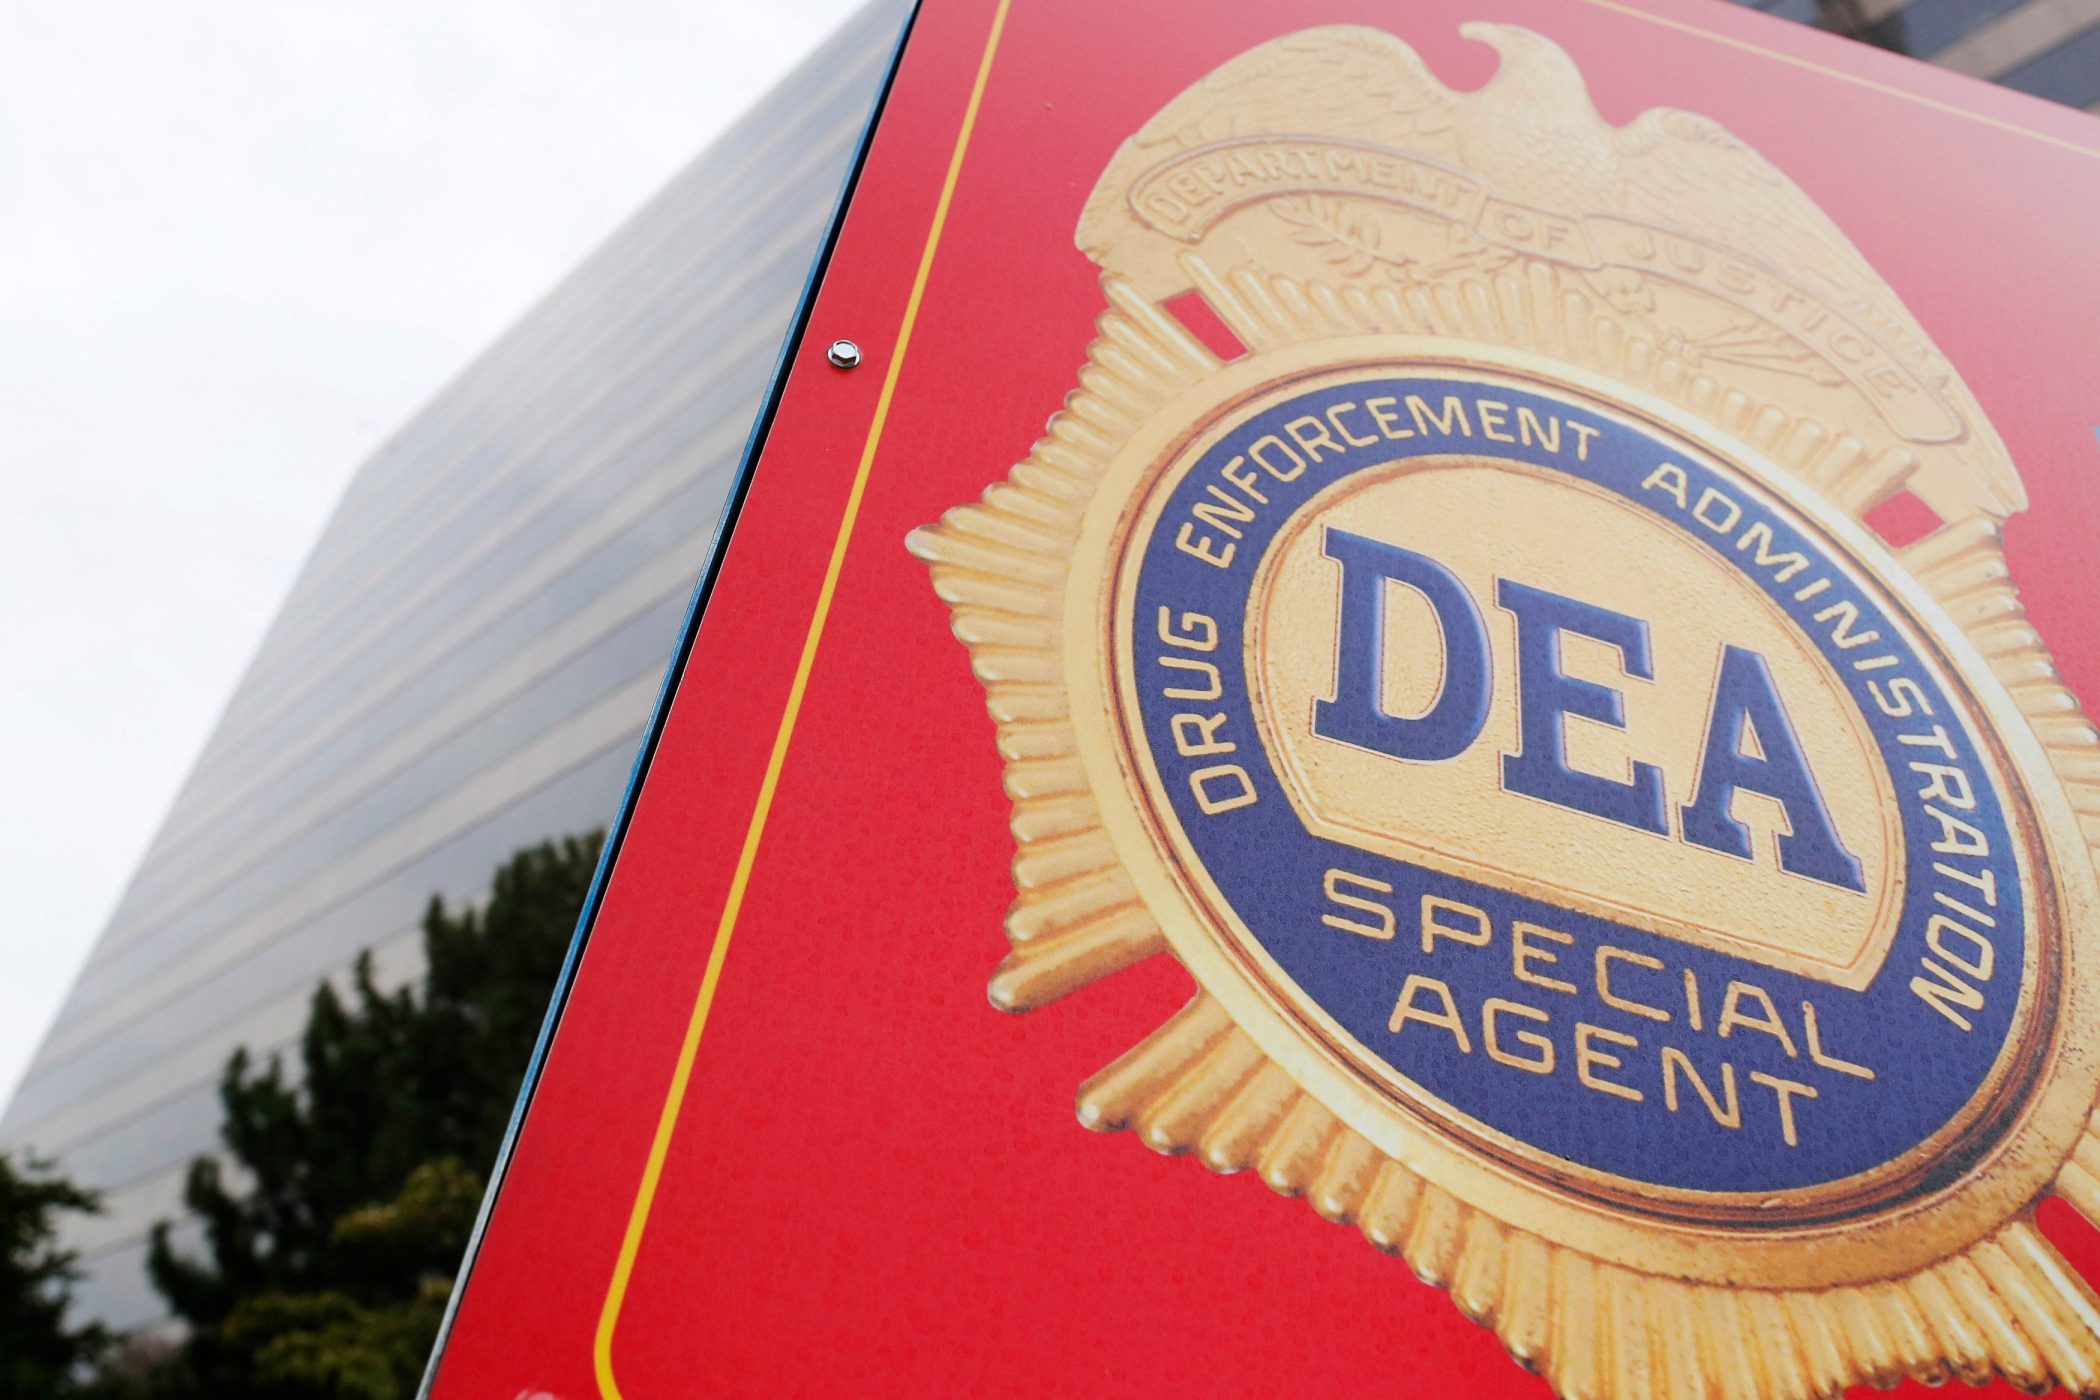
On October 30, the U.S. Department of Justice announced federal registrations for more than 900 medical Cannabis dispensaries in Alabama, Florida, Mississippi, South Dakota, Texas, Virginia and West Virginia. The approvals implement the administration’s April medical Cannabis rescheduling framework.[1]
For companies operating under licenses that combine medical and recreational sales, the route is less clear. That uncertainty has implications for business plans, projected tax savings and the assumptions investors use to value a company.
The problem with dual-purpose licenses
As HCN reported, the DEA has challenged Minneapolis-based In-Dispensary’s eligibility for federal registration under Minnesota’s dual-purpose licensing framework. The agency objects to a single license permitting both medical and non-medical dispensing.[2]
Its argument centers on diversion. Adult-use Cannabis remains outside the April medical rescheduling framework, and the DEA contends that Minnesota’s combined licensing structure does not provide sufficient protection against non-medical distribution.
The agency also raised concerns about physician certification requirements for certain veterans and products it characterizes as synthetic marijuana. The order gives In-Dispensary an opportunity to request a hearing or submit a corrective action plan. Minnesota regulators say it does not change state law or patients’ access to medical Cannabis.[2]
The decision raises concerns for other combined-market operators. It does not, by itself, establish that every medical business in a state permitting adult-use sales is ineligible.
What investors need to understand
The April action placed qualifying medical Cannabis in Schedule III. Cannabis outside that framework remains subject to Schedule I controls, with broader rescheduling being considered separately.[3]
That distinction matters when a company presents its growth strategy.
A medical revenue stream does not, on its own, demonstrate federal eligibility. Investors need to understand the authority granted by the company’s licenses, its patient qualification procedures and the operating changes federal compliance may require.
DOJ makes clear that state licensure alone does not confer federal registration. Applicants must satisfy federal requirements, and registered businesses face continuing obligations involving security, records and inventory controls.[1]
My view is that companies should resolve these questions before relying on federal recognition in an investment presentation. Identifying a licensing obstacle early gives management time to assess its options and explain the implications credibly.
Tax savings need a defensible foundation
Section 280E generally prevents businesses trafficking in Schedule I or II controlled substances from claiming deductions and credits. Schedule III treatment can therefore materially improve the economics of qualifying medical activities.[4]
But companies should be careful about presenting those savings as automatic.
Treasury and the IRS have said rescheduling generally removes the 280E restriction for activities that no longer involve Schedule I or II substances. They also anticipate guidance addressing companies with multiple activities, including the allocation of expenses.[4]
For a business serving both markets, federal registration and tax treatment require separate analysis. A financial model should explain which activities support the projected savings and what remains uncertain.
Supply chains also affect readiness
Federal eligibility extends beyond the dispensary.
DOJ says qualifying manufacturers, distributors and dispensaries that applied within the initial 60-day window may continue certain medical transactions while their applications remain pending, subject to the order’s requirements.[1]
Management therefore needs to understand the status of its trading partners as well as its own application. Supplier eligibility, continuity of inventory and potential compliance costs can all affect the use of proceeds and the capital required to execute a business plan.
Why we established Ready4DEA
We established Ready4DEA to help Cannabis operators understand and prepare for the federal medical registration process. Its purpose is to help companies assess their readiness, identify potential obstacles and develop a practical plan for addressing them.
For companies we meet through Safe Harbor Equity that are seeking capital, this can be a natural first step. If a business plans to use investment to expand its medical operations, pursue federal registration or build around anticipated tax savings, those assumptions need to be examined before they become part of the fundraising story.
Ready4DEA brings that preparation into focus: what the company’s licenses permit, how its operations align with federal requirements and what changes may be needed. That work can help management define its funding needs and give investors a clearer understanding of the proposed use of capital.
The starting point is a conversation about the business, its current position and its plans. From there, we can determine whether a readiness review would help move those plans forward.
Federal recognition creates an opportunity. Preparing for it can strengthen both the business and the case it makes to investors. Contact me here for more info on these initiatives.
Footnotes
[1] U.S. Department of Justice, October 30, 2026, “Justice Department Announces Issuance of Federal Registrations for Medical Marijuana Dispensaries.”
[2] HCN NewsTeam, November 2, 2026, “DEA Bars Dual-Purpose Dispensaries From Federal Medical Cannabis Registration.”
[3] U.S. Department of Justice, April 23, 2026, announcement of Schedule III treatment for qualifying medical Cannabis and a separate broader rescheduling proceeding.
[4] U.S. Department of the Treasury, April 23, 2026, “Treasury, IRS Announce Process for Tax Guidance Following DOJ Final Order on Medical Marijuana Rescheduling.”
About the Author:
Peter Ingersoll, CCIM, is CEO and Corporate Broker of Safe Harbor Equity, Inc., with 40+ years in finance, banking, investment real estate and business development. His Cannabis expertise covers capital advisory, M&A, valuation, property transactions, sale-leasebacks, growth financing, recapitalizations, reorganizations, startup equity, mezzanine debt, preferred equity and private placements.
Through Rescue Capital Group, he works on Cannabis receivership financing and loans for property, improvements, inventory, equipment and acquisitions. He founded Ready4DEA, a sister company of Safe Harbor Equity, to prepare operators for federal medical Cannabis registration through operational, governance, compliance and business planning.
His broader experience includes helping deploy approximately $22 million in 1031 exchange funds into self-storage acquisitions, raising bank holding company startup capital and securing 80% of a historic redevelopment project’s equity while in investment banking.
Peter is an expert witness in Cannabis valuation, investor, founder, creditor and fiduciary disputes. He holds a Wharton B.S. in Economics and the Certified Commercial Investment Member designation. He formerly held Series 7, 22 and 63 licenses and served as a Series 65 registered investment adviser.
About the Author: HCN News Team

Related Posts