Four Ways to Raise Capital in Cannabis. Only One Comes With a Wedding Registry.
By Peter Ingersoll, CEO of Safe Harbor Equity Inc., for HCN Media Group
SAN DIEGO- Raising capital will humble you. After more than four decades in finance, I can tell you it usually happens about twelve minutes into the first meeting.
You’ve spent six weeks getting the deck right. You’ve rehearsed the opening. Then someone flips straight to the financials and asks why your largest dispensary customer hasn’t paid you since March.
You explain that sales are growing. They ask whether collections are growing too.
You’ll learn a great deal about your Cannabis business in these meetings. You’ll also learn how many ways a grown adult can say “very interesting” without committing to a second meeting.
I count four ways to raise capital. Only one comes with a wedding registry.
1. You could marry into it.
The wedding is probably more fun than a due diligence call, and the open bar is a meaningful improvement over most investor conferences.
Still, if your financial model has a row labeled “marry well,” I’d leave it out of the base case.
Your prospective in-laws may also want to know why you built a cultivation facility before securing enough customers. Thanksgiving could become uncomfortable.
2. You could do it yourself.
You spend your evenings writing the business plan and your weekends building the deck. You hire someone on Upwork to make the slides look respectable. Then you ask AI for a list of Cannabis investors.
It gives you 200 names before you finish your coffee. By lunch, you’re still trying to find a working email address for the first ten.
Then you discover that one invests only in real estate, another wants profitable businesses, and a third stopped investing in Cannabis several years ago. His website remains enthusiastic.
Before sending the deck, get clear about what you need the money to accomplish. Funding a new extraction line is a different proposition from refinancing an expensive loan or covering overdue supplier invoices. Each requires a different explanation of how the business will repay lenders or create value for shareholders.
For a cultivator, that means explaining production costs, realized selling prices and what happens if wholesale prices fall. For a retailer, it means showing what remains after product costs, payroll, rent, taxes and discounts. For a manufacturer, it means distinguishing products shipped from invoices collected.
Record yourself giving the pitch and listen back. If you’re four minutes in and still explaining how you met your co-founder, imagine how the person who agreed to a fifteen-minute call feels.
There’s real value in doing it yourself. You hear objections firsthand, learn which parts of your story make sense outside your own conference room, and adjust on the next call.
The cost is your time. If your Cannabis business already needs you 60 hours a week, congratulations on your new evening job.
3. You could hire an investment banker.
A good investment banker with relevant Cannabis experience can help you structure the deal, identify suitable investors and keep the process moving while you run the business.
The relevant experience matters. Ask what transactions the team has completed, what role it played and whether those businesses resemble yours. Also understand who will approach investors and what registrations apply to that work.[1]
Then comes due diligence.
Someone asks for your facility lease, equipment liens, ownership records and the agreement with the investor who funded your first grow. You say, “Of course, I’ll send those right over,” with the confidence of a man who last saw them in a cardboard box during an office move.
Cannabis adds another layer. A proposed investment or acquisition needs to fit the ownership and financial-interest rules that apply to the business. In California, for example, the Department of Cannabis Control requires disclosures concerning owners and financial interest holders, including certain lenders. Ownership changes can also require regulatory review or a new license application.[2]
A banker can help organize the process. Your Cannabis attorney needs to address the licensing implications.
Neither can answer every operating question for you.
When an investor asks why your biggest wholesale customer left, why your newest store is missing its forecast or how you will fund the next production cycle, the answer has to come from management.
You were there. You know what happened. Investors want to know what you have done about it.
4. You could collaborate with a financial consultancy and a financial media platform.
This is the approach I favor. It combines financial preparation with a way to help people understand the business before a capital conversation begins.
At Safe Harbor Equity, we work with founders on the financial side, including capital requirements, transaction structure and business planning. We also work with HCN Media Group, whose Cannabis financial news network publishes this column.
The starting point is a business that can explain itself.
A cultivator might discuss how it improved consistency and reduced production costs. A manufacturer might explain how it turns repeat orders into dependable margins. A retailer might describe what brings customers back without another discount.
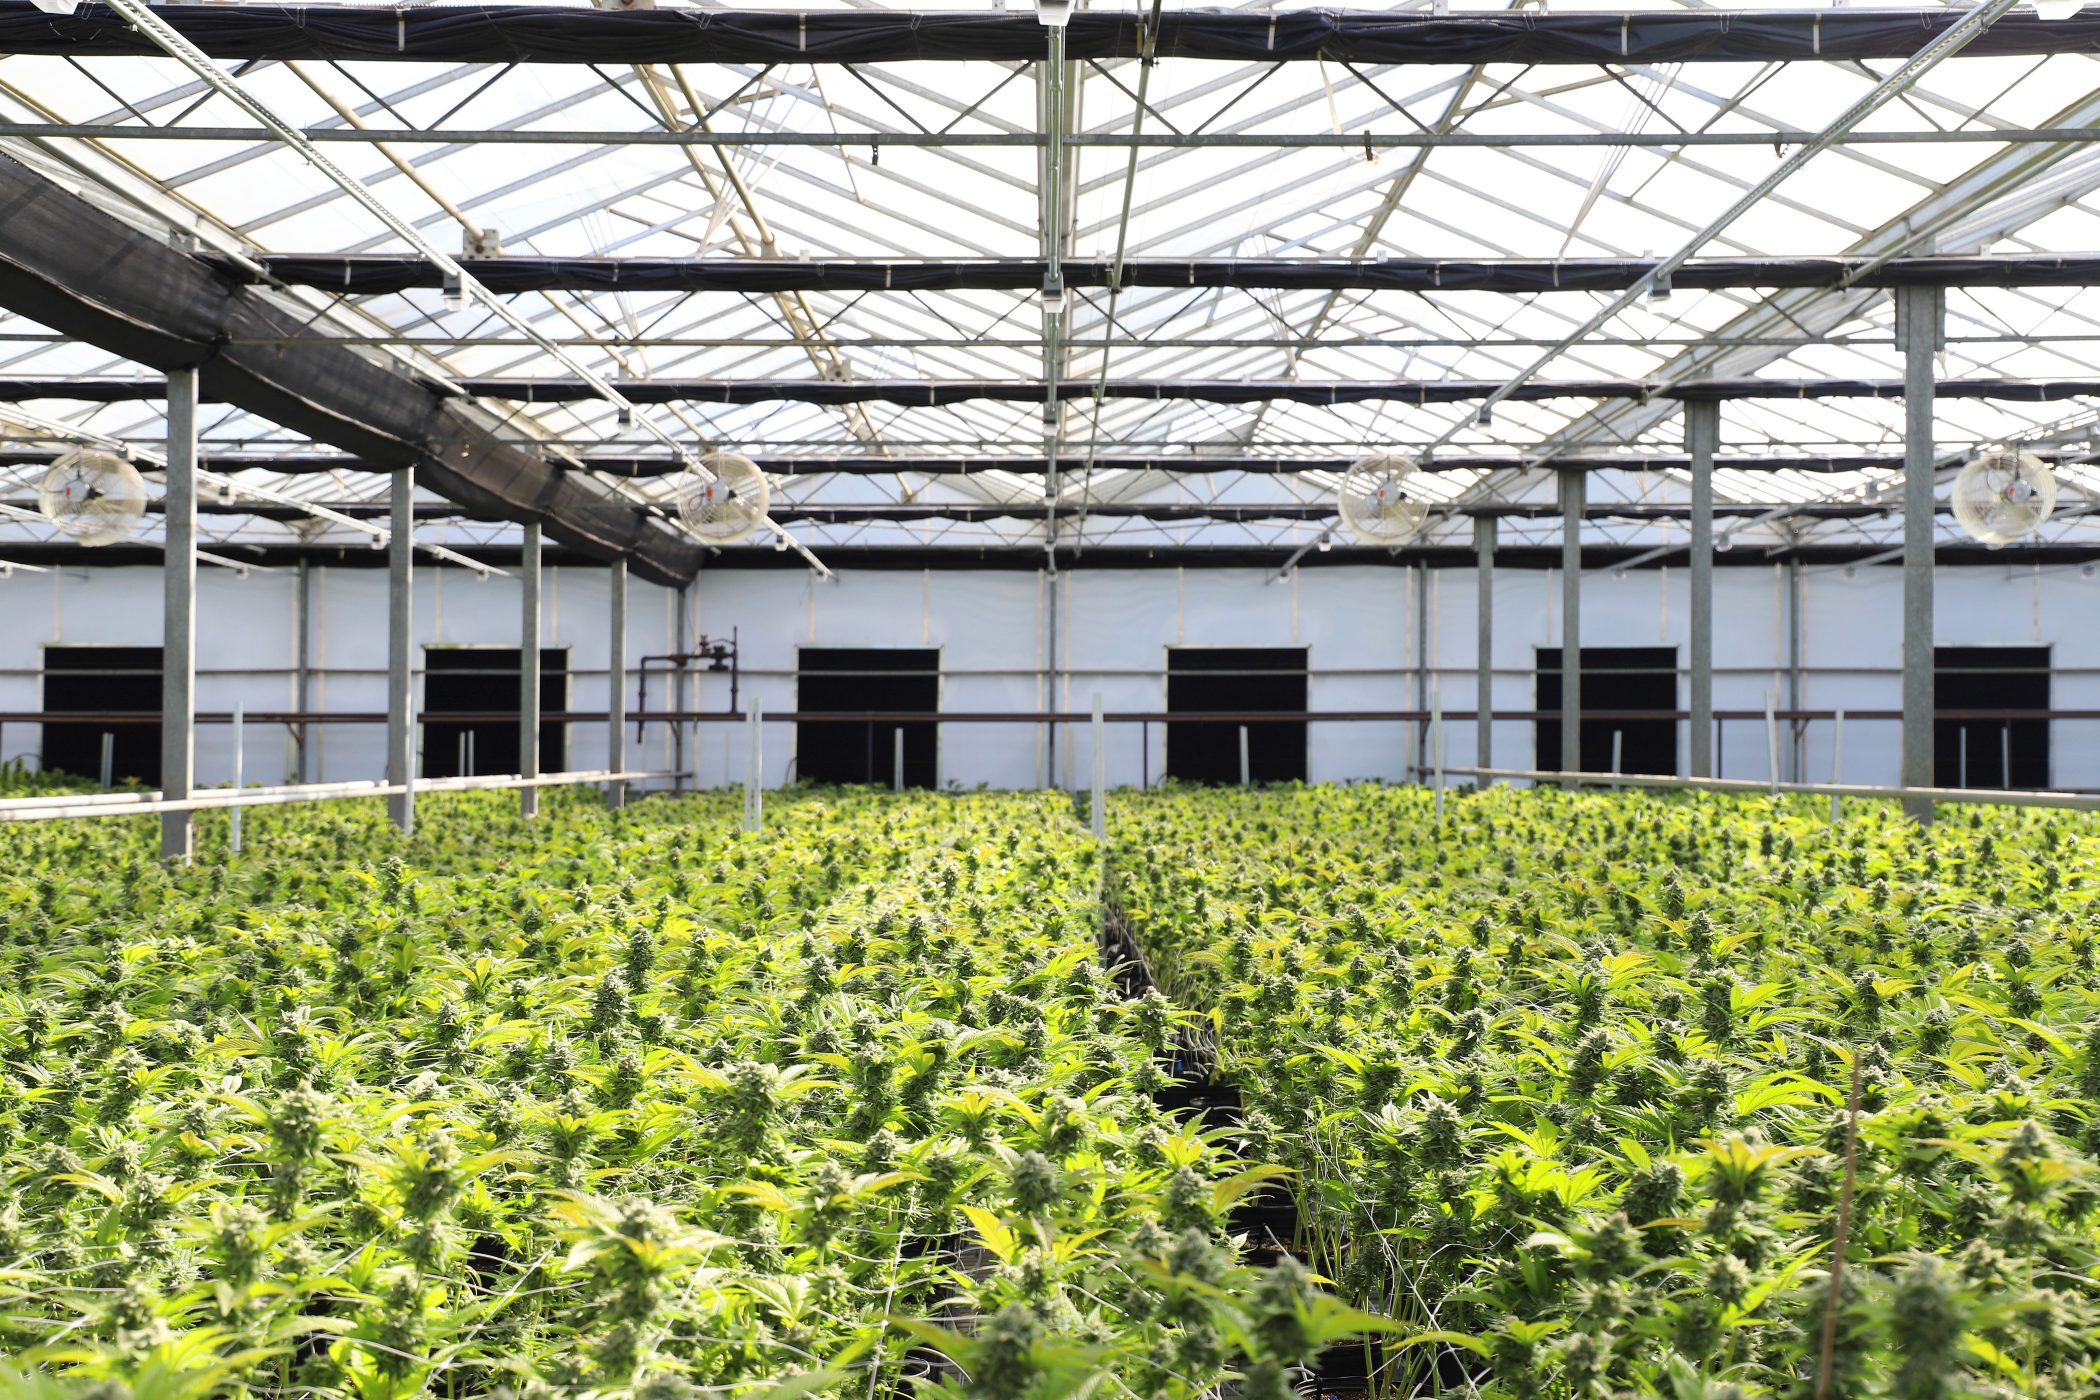
An interview, article or newsletter can make those operating details understandable. It gives people something more useful than another photograph of a greenhouse accompanied by the words “massive opportunity.”
Where readers choose to share their details and agree to follow-up, their interest can provide a starting point for a conversation. A report download tells you that someone was curious. It does not establish that they are a qualified investor or ready to write a check.
Public communications also need to fit the legal structure of the raise. Rule 506(b) generally prohibits general solicitation. Rule 506(c) permits it under specified conditions, including that all purchasers are accredited investors and that the issuer takes reasonable steps to verify their status. Plan offering-related communications with securities counsel before publication.[3]
Financial consulting, media work and securities placement each have their own responsibilities. Where an activity requires a registered securities intermediary, the appropriate registered firm needs to handle it.[1]
The founder still has to explain where the margin comes from, how much cash the business needs and what happens if prices fall.
A good interview can get someone curious enough to open the spreadsheet. The spreadsheet, sadly, has no sense of humor.
Stay close enough to hear what prospective investors are actually saying. If three ask how much revenue comes from your biggest customer, answer that question up front in the next meeting.
If several like the business but hesitate over the same deal term, find out why. You may learn something that changes the offer as well as the pitch.
And if everyone asks how the company survives without another raise, you probably need a better answer than “the market is coming back.”
The raise ends. The relationships carry on.
A growing Cannabis company may need capital again for an expansion, an acquisition or a chance to buy a competitor’s equipment at a price that makes you wish you’d never bought yours new.
By then, the banker you met two years ago may have changed firms. The investor who passed may have a different mandate. Someone who was a poor fit for the deal may turn out to be an excellent strategic partner.
That’s where I see the long-term value of staying involved.
Keep in touch when you have something worth sharing. A short note about a customer win, improved collections or a milestone you reached is plenty. If you missed a target, explain what happened and what you changed.
There’s a special warmth to hearing from someone for the first time in two years and discovering, by the second paragraph, that they need $5 million by Friday.
About the author
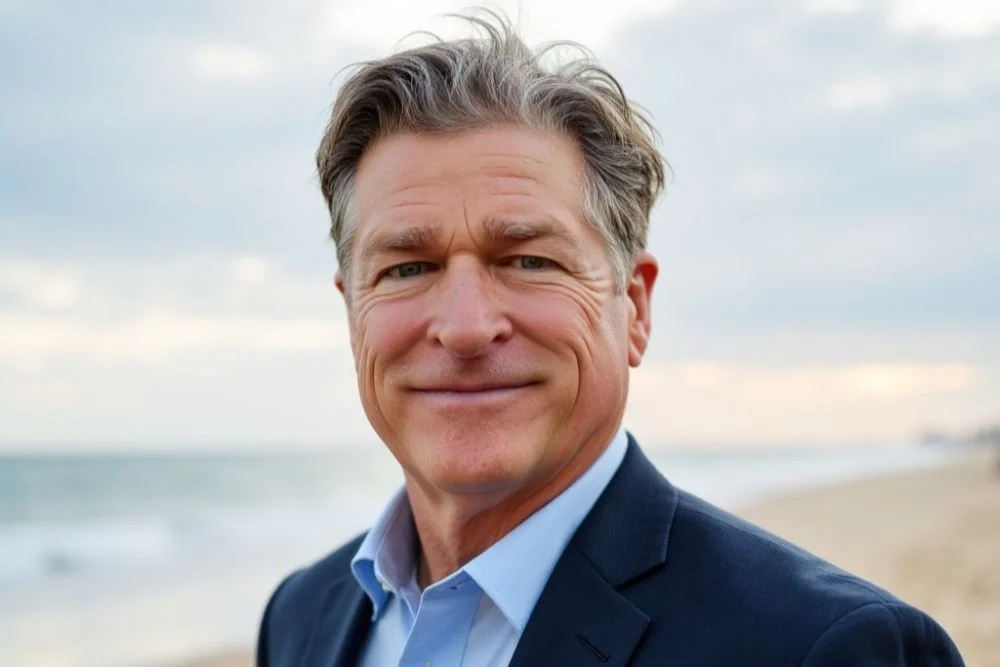
Peter Ingersoll, CCIM, is CEO and Corporate Broker of Safe Harbor Equity, Inc., with more than 40 years of experience in finance, banking, investment real estate and business development. His Cannabis expertise includes capital advisory, mergers and acquisitions, valuation, property transactions, sale-leasebacks, growth financing, recapitalizations, reorganizations, startup equity, mezzanine debt, preferred equity and private placements.
He formerly served as Cannabis product chair for Sperry Commercial Global Affiliates, an Orange County–based national real estate firm. Through Rescue Capital Group, he worked on Cannabis receivership financing and loans for property, improvements, inventory, equipment and acquisitions.
He founded Ready4DEA, a sister company of Safe Harbor Equity, to prepare operators for federal medical Cannabis registration through operational, governance, compliance and business planning. His role with The Panther Group is to oversee deployment of Panther’s capital aggregation and allocation model.
His broader experience includes helping deploy approximately $22 million in 1031 exchange funds into self-storage acquisitions, raising startup capital for a bank holding company and securing 80% of a historic redevelopment project’s equity while in investment banking.
Peter is an expert witness in Cannabis valuation and disputes involving investors, founders, creditors and fiduciaries. He holds a B.S. in Economics from Wharton and the Certified Commercial Investment Member designation. He formerly held Series 7, 22 and 63 licenses and served as a Series 65 registered investment adviser.
Footnotes
[1] U.S. Securities and Exchange Commission, “Broker-Dealers.” The SEC identifies investor solicitation, negotiation, transaction participation and compensation tied to a transaction’s outcome or size among the factors relevant to broker registration. A corporate real estate broker title or previously held securities licenses do not establish current broker-dealer registration. [2] California Department of Cannabis Control, “Text of Regulations,” sections 15003, 15004 and 15023. These provisions address owners, financial interest holders and business modifications. Requirements differ by jurisdiction and transaction structure. [3] U.S. Securities and Exchange Commission, “Exempt Offerings” and “Assessing Accredited Investors under Regulation D.” Whether a particular communication constitutes general solicitation depends on its facts and circumstances.About the Author: HCN News Team

Related Posts